Tokyo's economy contracted an annualised 0.1 per cent in the July-September quarter, government data showed on Monday, the first shrinkage in four quarters and a miss against the 0.3 per cent growth economists polled by Reuters had expected, according to CNA.
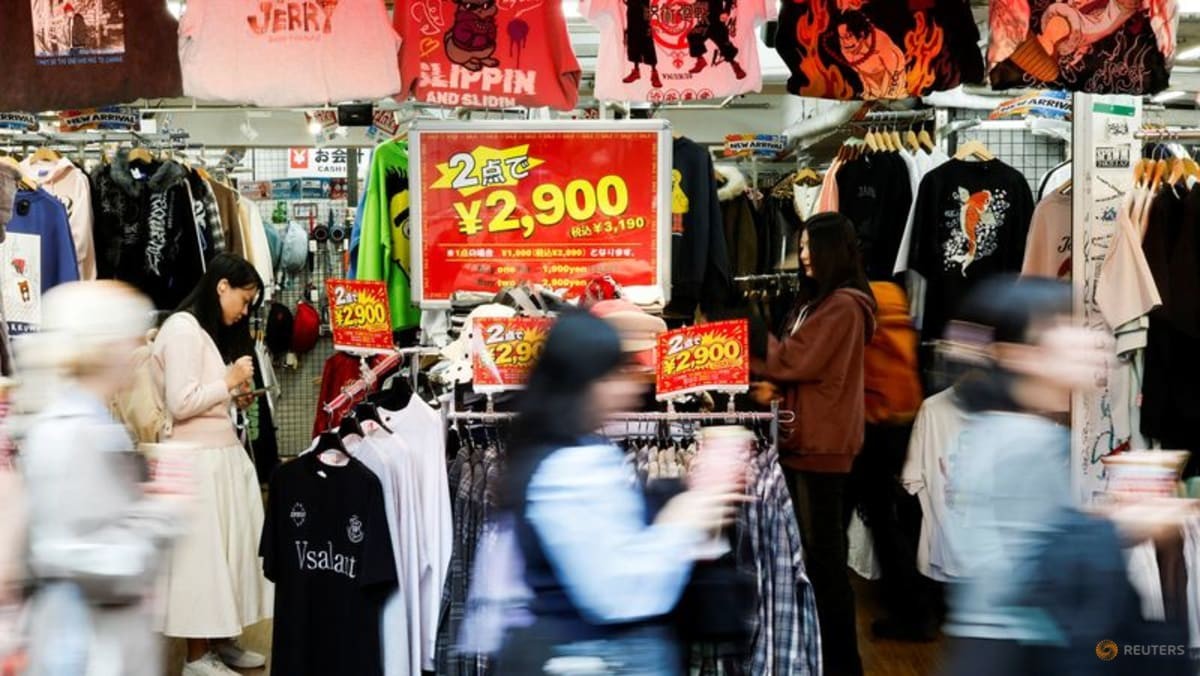
The surprise dip, a fall of 0.02 per cent on a quarterly basis, reflects a consumer sector under strain. Private consumption, which makes up more than half of Japanese output, declined 0.3 per cent as households absorbed sustained price increases. For regional watchers, the numbers are a reminder that even advanced economies in Asia face the same inflation-versus-growth balancing act that Singapore and its neighbours have been managing since 2022.
What the GDP data shows
The contraction followed a revised 1.7 per cent annualised expansion in the April-June quarter. Market forecasts had pencilled in a 0.1 per cent quarterly increase, according to Reuters data carried by Investing.com.
Household spending was dented by persistent price pressures and unusually poor weather, including heavy rain and typhoons during the quarter. Demand for automobiles and air conditioners also retreated after a temporary boost in the previous quarter from tax and regulatory changes, a hangover effect economists call the danpatto, the post-incentive slump.
Private consumption fell 0.3 per cent, worse than the 0.2 per cent decline the market expected.
Yet the broader picture is less gloomy than the headline suggests. Capital spending rose 1.6 per cent, beating the 1.5 per cent forecast, supported by investment in labour-saving technologies and artificial intelligence-related projects. Corporate activity has stayed resilient even as the consumer wobbled.
Strong wage growth should support consumption, but higher prices linked to Middle East tensions will continue to squeeze household purchasing power.
That assessment came from Masato Koike, senior economist at Sompo Institute Plus.
Why the Bank of Japan is unlikely to blink
Policymakers are not expected to treat the negative print as a brake on Japan's moderate recovery. Rising real wages, firm corporate investment and AI-related demand continue to underpin growth.
While growth was indeed negative this time, there is no need to be overly pessimistic about the result, said Kento Minami, senior economist at Daiwa Securities. His impression is that moderate growth is probably continuing.
Minami added that the figures are unlikely to derail the Bank of Japan's tightening path. The central bank remains focused on inflation risks, and with firm domestic price pressures plus a global backdrop of higher interest rates, a dovish pivot looks improbable.
The BOJ has already delivered rate hikes in June and September this year, responding to stubbornly high energy costs and rising import prices from a weak yen. Many analysts expect the next hike as soon as December, The Business Times reported.
Trade and energy: the external drag
Net external demand, exports minus imports, subtracted 0.6 percentage point from growth, more than the 0.4 point drag markets had forecast. The culprit was a sharp rise in imports, as oil and energy purchases recovered after Japan diversified procurement following disruptions linked to the war in the Middle East.
The episode illustrates a lesson familiar to Singapore planners: energy security is supply-chain management, not just geopolitics. Japan's procurement pivot cushioned the initial shock but is now feeding back into the import bill.
What comes next for Japan's growth path
A monthly survey of 37 economists by the Japan Center for Economic Research projects growth of 0.89 per cent in fiscal 2026 and 1.02 per cent in fiscal 2027, a modest but resilient trajectory.
The longer-term picture is less comfortable. The International Monetary Fund projects Japan will slip to the world's sixth-largest economy in nominal dollar terms by 2027, overtaken by India and Britain. Japan currently ranks fourth, behind Germany.
For ASEAN economies, the implications cut both ways. A tightening BOJ narrows the interest-rate differential that has long favoured regional carry trades and cheap dollar funding. At the same time, Japan's AI investment boom and corporate capex resilience offer demand for Southeast Asian components, data centre capacity and services.
The December BOJ meeting is the next checkpoint. Markets will be watching whether the bank prioritises inflation risks over a single soft quarter, and whether the yen's weakness continues to import the price pressures that started this cycle in the first place.
Frequently asked questions
How much did Japan's economy shrink in July-September?
GDP contracted an annualised 0.1 per cent, or 0.02 per cent quarter on quarter, according to government data released on Nov 16.
Why did Japanese consumption fall?
Households faced persistent inflation, poor weather including typhoons, and a pullback in car and air conditioner demand after the previous quarter's tax and regulatory boosts.
Will the Bank of Japan still raise rates?
Most analysts expect the next hike as soon as December, as the bank prioritises inflation risks over one weak quarter, according to Daiwa Securities and The Business Times.